
By Romain Picard, Partner – Corporate Department
When it comes to controlling foreign investment, it is well understood that the temporary always has the potential to become permanent!
The 10% threshold of voting rights provides an illustration of this. It was introduced as a crisis measure by Decree No. 2020-892 of July 22, 2020, published in the Official Journal of July 23, 2020, in the context of the Covid-19 pandemic. The rule was not codified at the time: it appeared in Article 1 of the decree itself, according to which, "until December 31, 2020," crossing, directly or indirectly, alone or in concert, the 10% threshold of voting rights in a French company whose shares are admitted to trading on a regulated market constituted an investment within the meaning of Article L. 151-3 of the French Monetary and Financial Code.
Its initial duration was only about five months.
Three one-year extensions followed:
- Decree No. 2020-1729 of December 28, 2020 postponed the deadline to December 31, 2021;
- Decree No. 2021-1758 of December 22, 2021 to December 31, 2022; then
- Decree No. 2022-1622 of December 23, 2022 to December 31, 2023.
Decree No. 2023-1293 of December 28, 2023, applicable from January 1, 2024, ended this temporary regime: the measure was removed from the scope of crisis measures and codified in paragraph 4 of Article R. 151-2 of the Monetary and Financial Code, without time limit. The reform of summer 2026 extends this trend: it not only broadens the 10% threshold but also confirms its permanent establishment in the law governing foreign investment control.
Decree No. 2026-718 of July 30, 2026, and an order issued the same day, published in the Official Journal on August 2, 2026, thus complete the French system for controlling foreign investments. The reform entered into force on August 17, 2026.
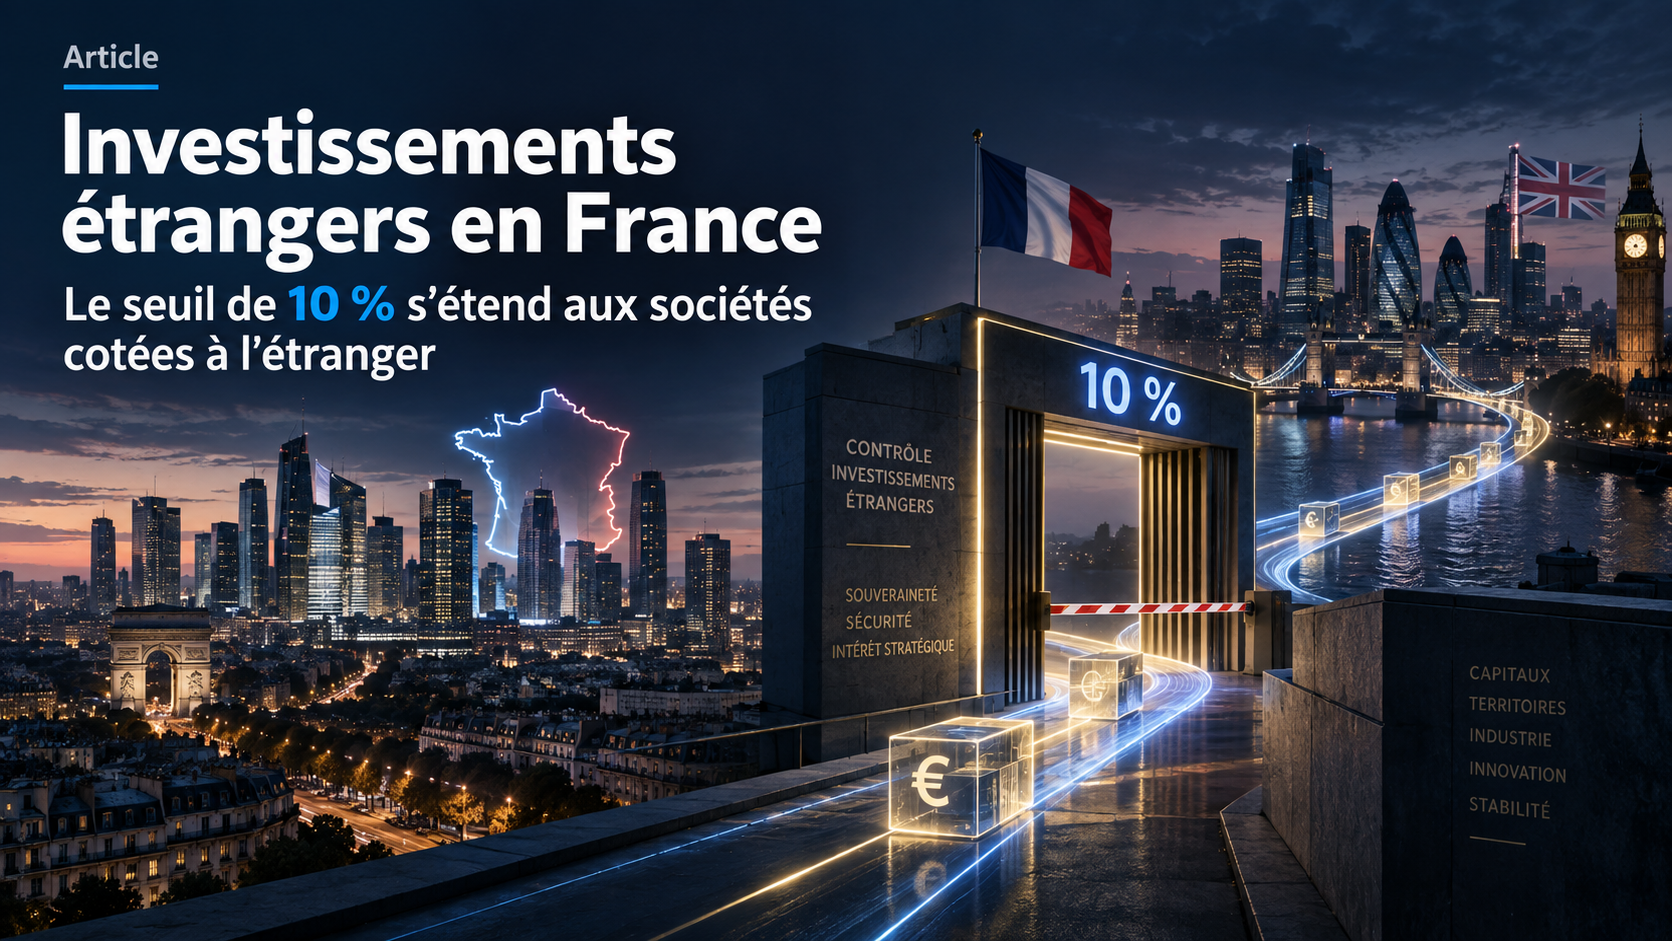
Their purpose may seem technical. However, their consequence is very concrete: listing a French company on a foreign financial market no longer necessarily allows it to escape the control applicable to crossing the 10% threshold of voting rights.
Since August 17, 2026, foreign investment control in France has extended to certain shareholdings in French companies listed on foreign markets. Exceeding the 10% threshold of voting rights by a non-European investor or a non-national of the European Economic Area may now require prior notification or even a request for prior authorization of foreign investment from the Ministry of the Economy and Finance (Bercy), particularly when the French company carries out a sensitive activity (for the exhaustive list: Article R. 151-3 of the Monetary and Financial Code and the Order of December 31, 2019 relating to foreign investments in France, as consolidated on August 17, 2026).
An acquisition of a stake in a French company listed in New York, London, Zurich, Toronto, Singapore, Tokyo or Seoul may therefore have to be notified to the Minister in charge of the Economy.
However, several conditions must be met: not every acquisition of 10% of the voting rights of a French company listed abroad is automatically subject to control by Bercy.
I – The control of foreign investments in France does not only concern takeovers
The control of foreign investments in France, known as "FDI control", allows the Minister in charge of the Economy to control certain operations carried out by foreign investors in French companies engaged in activities likely to affect public order, public safety or national defense interests.
Therefore, it does not indiscriminately concern all French companies and all foreign investors.
The system can notably be applied to:
- the acquisition of control of a French legal entity;
- the acquisition of all or part of a business branch of a French entity;
- the crossing, directly or indirectly, alone or in concert, by an investor outside the European Union or the European Economic Area, of the 25% threshold of voting rights of a French entity;
- the crossing, by this same type of investor, directly or indirectly, alone or in concert, of the 10% threshold of voting rights of a French company whose shares are admitted to trading on a regulated market.
II – Foreign listing constituted a limitation to the system
Until now, the wording of the texts could leave outside the specific scope of the 10% threshold certain French companies whose securities were admitted to trading on a financial market located outside the European Union or the European Economic Area.
This situation created a difference in treatment depending on the market on which the French company was listed.
It also contributed to making Paris less attractive as a listing location: for comparable activities, shareholdings, and investment projects, a French company admitted to trading on Euronext Paris fell under the 10% threshold, while a company listed on certain foreign stock exchanges could avoid it. Listing in France thus became an additional factor of exposure to IEF control, which could be taken into account by both issuers and non-European investors.
Decree No. 2026-718 of July 30, 2026 now supplements Article R. 151-2 of the Monetary and Financial Code in order to take into account French companies whose shares are admitted to trading on foreign regulated markets designated by decree.
III – Which foreign markets are concerned?
Thedecree of July 30, 2026 determines the markets considered to be regulated for the application of the control.
This includes, in particular:
- the London Stock Exchange in the United Kingdom;
- the SIX Swiss Exchange in Switzerland;
- the Toronto Stock Exchange in Canada;
- the Singapore Exchange in Singapore;
- the Japan Exchange in Japan; and
- the Korea Exchange in South Korea.
The scheme also covers markets located in a third country benefiting from an equivalence decision by the European Commission.
This is notably the case for the main American stock exchanges — the New York Stock Exchange, The Nasdaq Stock Market and the Chicago Stock Exchange (now NYSE Chicago) —, the United States having benefited from such equivalence since Commission Implementing Decision (EU) 2017/2320 of 13 December 2017 on the equivalence of the legal framework and supervisory system of the United States of America applicable to national stock exchanges and alternative trading facilities, in accordance with Directive 2014/65/EU of the European Parliament and of the Council.
A company incorporated under French law whose shares are admitted to trading on one of these exchanges is therefore likely to fall under the 10% threshold.
And this is no coincidence: many French high-tech companies—in quantum computing, artificial intelligence, additive manufacturing, and robotics—are specifically eyeing foreign listings, particularly American ones, to raise the capital necessary for their development. These are also the companies whose activities most directly fall under the critical technologies targeted by the decree of December 31, 2019. Choosing a listing outside the European Union therefore no longer places them outside the 10% threshold.
The list of relevant markets now constitutes a control point in its own right in the IEF analysis of an acquisition or investment project.
It is therefore no longer sufficient to simply note that the target company is incorporated under French law and that its securities are traded abroad. It is necessary to precisely identify the listing venue and verify whether it falls within the scope defined by the decree.
IV – Not all 10% acquisitions are affected
The title of this contribution calls for an essential clarification: the acquisition of 10% of a French company listed in London is not, in principle, subject to the control of Bercy.
Several cumulative conditions must be met.
A. The target must be an entity governed by French law
The system is based first on the law applicable to the target company: only entities governed by French law fall within its scope.
The location of its shareholders, customers, assets or listing market is, at this stage of the analysis, irrelevant: it neither creates nor excludes the Minister's jurisdiction.
B. The company must carry out a sensitive activity
The IEF control only applies if the target company carries out an activity falling within the scope of Article R. 151-3 of the Monetary and Financial Code.
Activities that may be affected include:
- to weapons, ammunition, powders and explosive substances intended for military purposes or to war materiel and related items;
- to dual-use goods and technologies;
- to information systems security;
- to the means and services of cryptography;
- to technical equipment or devices capable of intercepting communications or designed for the remote detection of conversations or the capture of computer data;
- gambling, with the exception of casinos;
- to the integrity, security or continuity of energy and water supply, transport networks and services, space operations and electronic communications networks and services;
- to the exercise of the missions of the national police, the national gendarmerie, the civil security services, and the security of penitentiary establishments;
- to the integrity, security or continuity of operation of an establishment, installation or structure of vital importance;
- to the protection of public health;
- to the production, processing or distribution of agricultural products, when these activities contribute to national food security objectives;
- to the editing, printing or distribution of press publications of political and general information;
- to the integrity, security, or continuity of the extraction, processing, and recycling of critical raw materials; and
- to research and development activities relating to critical technologies, thedecree of December 31, 2019 relating to foreign investments in France aims in this respect at: cybersecurity; artificial intelligence; robotics; additive manufacturing; semiconductors; quantum technologies; energy storage; biotechnologies; technologies involved in the production of low carbon energy and photonics.
The qualification must be carried out concretely. The corporate purpose appearing in the articles of association is not always sufficient to determine whether the actual activity, "even on an occasional basis" (article L. 151-3 of the Monetary and Financial Code) of the company falls within the scope of control.
C. The investor must be from outside the European Union or the European Economic Area
Crossing the 10% threshold concerns investors not from the European Union or the European Economic Area under the conditions provided for by the Monetary and Financial Code.
The analysis should not stop at the identity of the company that directly carries out the acquisition.
The investor's chain of control must be reconstructed to identify the persons or entities that ultimately control them. An acquisition company established in a Member State may therefore not be sufficient to exclude control when its parent company, a company in the chain of control, or its ultimate beneficial owner is established in a third country.
D. The 10% threshold of voting rights must be crossed
The text targets voting rights, and not just the fraction of capital held.
Therefore, we must examine:
- the securities already held by the investor;
- voting rights attached to the different categories of shares;
- instruments that can provide access to capital or voting rights;
- direct and indirect detentions; and
- possible concerted actions.
An apparently limited operation can thus trigger control when it leads the investor, alone or in concert, to cross the regulatory threshold.
E. The shares must be traded on one of the specified markets
Finally, the French company must be listed on a market included in the list established by thedecree of July 30, 2026 or benefiting from the required European equivalence.
The mere generic reference to a "foreign listing" is therefore not sufficient.
F. A simplified, but mandatory, prior notification
Crossing the 10% threshold is subject to a specific procedure.
The investor is exempt from immediately submitting a complete application for foreign investment authorization in France provided that prior notification is sent to the Minister for the Economy, in accordance with the last paragraph of Article R. 151-5 of the Monetary and Financial Code.
From the date of this notification, the minister has ten working days to object to the exemption from the request for authorization.
Two situations can then arise.
In the absence of any objection within this period, the investor benefits from an exemption from requesting authorization and may carry out the operation under the declared conditions.
If there is an objection, the investor must submit a complete application for prior authorization of foreign investment in France. The transaction cannot then be carried out until the minister's decision is received.
The short time frame should not be misleading: the notification is prepared in advance, just like a filing for prior authorization of foreign investment in France.
Preparing the case requires having precise information about the investor, its chain of control, its shareholding, its intentions and the activities of the target company.
Uncertainty about the eligibility of the activity may also justify the filing of a prior request for examination of an activity — IEF ruling provided for in Article R. 151-4 of the Monetary and Financial Code — with the Minister in charge of the Economy, examined by the Directorate General of the Treasury, the Minister having a period of two months to respond.
V – IEF control must be anticipated from the outset of the operation's structuring
The reform requires investors, managers and advisors more than ever to raise the issue of IEF control from the very first preparatory work.
A delayed check can have several consequences:
- necessitate a change in the closing schedule and consequently delay the change of control of the target company or the resulting fundraising;
- to force the parties to renegotiate the suspensive conditions;
- prevent anticipating the conditions that the minister may attach to his authorization pursuant to Article R. 151-8 of the Monetary and Financial Code;
- weaken the financing of the acquisition;
- expose the investor to the risk of an irregular execution of the transaction.
Letters of intent, investment protocols, transfer contracts and shareholder agreements must therefore include, where relevant, a suspensive condition relating to obtaining authorization or the absence of opposition from the minister.
The parties must also contractually arrange:
- the responsibility and schedule for preparing and submitting the application;
- the transmission of the necessary information by the target company;
- the cooperation of the investor, the seller and the target company – particularly with regard to any Q&A from the ministry (it is recalled that the processing times provided for by the IEF regulations only run from the receipt of a complete file, so that any request for additional information from the ministry suspends this period in practice);
- the consequences of any conditions imposed by the minister;
- the deadline for completing the operation;
- the consequences of a refusal or opposition.
VI – Best practices to remember: what checks should be carried out before the operation?
Before any foreign investment in a listed French company, a six-step analysis can be carried out.
First step: identify the target
It is necessary to verify that the target is a French legal entity and to precisely identify its listing market(s).
Second step: defining your activities
The activities actually carried out, even on an occasional basis, must be compared to the list of sensitive sectors provided for in the Monetary and Financial Code.
This analysis should also cover subsidiaries, strategic contracts, technologies developed, and research and development activities.
Third step: Reconstruct the investor's chain of control
It is necessary to identify all the entities comprising the ownership chain, as well as the ultimate investor and, where applicable, its links with a foreign state or public body.
Fourth step: calculating voting rights
The calculation must include prior shareholdings, indirect holdings, instruments giving access to voting rights and any concerted actions.
Fifth step: determine the applicable procedure
Depending on the nature of the operation, prior notification, a full application for authorization or a prior request for review of the activity may be required.
Sixth step: adapt the contractual documentation
The timetable, conditions precedent, cooperation commitments and the consequences of an unfavorable decision must be included in the agreements concluded between the parties.
VII – The consequences of an operation carried out without prior control
Ignorance of the foreign investment regime is not a simple administrative irregularity.
When the operation has been carried out without prior authorization, even though it was necessary, the minister may, in particular, order the investor to:
- to submit an application for authorization;
- to modify the operation;
- to restore, at its own expense, the previous situation.
Protective measures and penalties may also be imposed on the basis of Article L. 151-3-1 of the Monetary and Financial Code, the daily amount of the penalty not being able to exceed 50,000 euros.
The investor is also exposed to significant financial penalties, the amount of which may be calculated based on the value of the investment or the turnover of the company concerned.
The risk is not only administrative. Article L. 151-4 of the Monetary and Financial Code renders null and void any commitment, agreement or contractual clause carrying out, directly or indirectly, a foreign investment without the required authorization, and Article L. 165-1 of the same code refers to Article 459 of the Customs Code for the criminal aspect.
The omission of IEF control can therefore affect the validity of the transaction itself, its governance and the rights attached to the acquired participation.
Conclusion – A targeted but significant development for international operations
The reform of July 30, 2026, does not subject all foreign acquisitions to new controls. It does not modify either the general list of sensitive activities or, strictly speaking, the 10% threshold already applicable to listed companies.
However, it closes an important loophole by extending this threshold to French companies listed on several major foreign financial markets.
Since August 17, 2026, the location of the listing market, the nationality of the ultimate investor and the nature of the target's business must therefore be examined jointly.
In practice, IEF control moves from the periphery of due diligence to the first points of the execution checklist : identification of the listing venue, tracing back through the chain of control and qualification of activities must be addressed from the structuring of the investment.
Reference texts
- Decree No. 2026-718 of July 30, 2026 relating to foreign investments in France, published in the Official Journal of August 2, 2026;
- Order of 30 July 2026 relating to foreign investments in France, published in the Official Journal of 2 August 2026;
- Articles L. 151-3 et seq. and R. 151-1 et seq. of the Monetary and Financial Code;
- Order of 31 December 2019 relating to foreign investments in France, in its consolidated version as of 17 August 2026.
Romain Picard
Author
Family SCI or joint ownership: which structure to choose for a family property purchase?
By Olivier Paquerau, of counsel at ARST Avocats. Buying a home, a rental property, or a family residence with several people quickly leads to a fundamental question: should you buy jointly or form a real estate company?...
Investing in rental housing in French Guiana: what tax credit is available for companies subject to corporate income tax?
Companies subject to corporation tax that invest in new rental housing in French Guiana can benefit, under certain conditions, from a tax credit of 40% under Article 244 quater X or 35% under Article 244 quater W of the French General Tax Code.
End of season in the Médoc: what to do when your company's cash flow is insufficient?
After a difficult 2026 tourist season, some businesses in the Médoc region are entering autumn with insufficient cash flow. Payment deadlines, negotiations with creditors, ad hoc mandates, conciliation, or insolvency proceedings: the solutions depend on the severity and origin of the difficulties.
Surviving spouse and blocked inheritance: what rights and what recourse?
When a married person dies, their spouse benefits from significant inheritance rights. They can receive a share of the estate outright or as a life estate, retain the right to use the family home, and be completely exempt from inheritance tax. This...
Overturning of a court-ordered liquidation: the company is saved
The court overturns the judgment - Episode 4/4 This story is inspired by a true case. Some details have been changed to protect the anonymity of those involved. On the day of the appeal hearing, the company still exists. The employees are still...
Judicial liquidation suspended: is the company still at risk?
Living in law, vulnerable in reality - Episode 3/4 This story is inspired by a true case. Some elements have been changed to protect the anonymity of those involved. The presiding judge's decision is a victory. When the...
Suspending a judicial liquidation: the hearing that needed to be brought about
The Audience That Had to Be Provoked - Episode 2/4 This story is inspired by a true case. Some details have been changed to protect the anonymity of those involved. Just a few days. That's all that's left to prevent the liquidation of...
Company liquidated without its knowledge: the beginning of a legal battle
Madam, your company has been liquidated - Episode 1/4 This story is inspired by a true case. Some details have been changed to protect the anonymity of those involved. The phone rings early this Monday morning. On the other end of the line is one of the key...
Employment of older workers: the negotiation that 9 out of 10 companies are still unaware of
Companies with at least 300 employees and representative union sections must negotiate on the employment of older workers. Preliminary assessment, job retention, end-of-career planning, skills transfer, and the risk of penalties: these are the measures to anticipate.
Workplace accident: the rules for your compensation are changing
Recognition of the employer's inexcusable negligence allows the victim of a workplace accident or occupational disease to obtain additional compensation. Since the standard workplace accident/occupational disease annuity no longer covers permanent functional impairment, new categories of damages can be compensated.
Family SCI or joint ownership: which structure to choose for a family property purchase?
By Olivier Paquerau, of counsel at ARST Avocats. Buying a home, a rental property, or a family residence with several people quickly leads to a fundamental question: should you buy jointly or form a real estate company?...
Investing in rental housing in French Guiana: what tax credit is available for companies subject to corporate income tax?
Companies subject to corporation tax that invest in new rental housing in French Guiana can benefit, under certain conditions, from a tax credit of 40% under Article 244 quater X or 35% under Article 244 quater W of the French General Tax Code.
End of season in the Médoc: what to do when your company's cash flow is insufficient?
After a difficult 2026 tourist season, some businesses in the Médoc region are entering autumn with insufficient cash flow. Payment deadlines, negotiations with creditors, ad hoc mandates, conciliation, or insolvency proceedings: the solutions depend on the severity and origin of the difficulties.
